

Автор: admin
Insurances
for small businesses
in New York
New York state law requires each business that has representatives, full-time or low maintenance, to convey laborers’ remuneration protection. This strategy covers doctor’s visit expenses for work wounds and shields businesses from obligation over the damage.
All business-claimed vehicles in New York must be secured by business collision protection.
In spite of the fact that it’s not required, individual vehicles driven for work purposes ought to be secured by enlisted and non-possessed accident coverage, as close to home auto approaches, for the most part, prohibit business use.
In spite of the fact that it’s not required, individual vehicles driven for work purposes ought to be secured by enlisted and non-possessed accident coverage, as close to home auto approaches, for the most part, prohibit business use.
It very well may be added to general risk protection or an entrepreneur’s approach.

Suggested protection approaches
for Insurances for small businesses in New York
General obligation protection
General obligation protection covers client wounds, client property harm, and related claims. It’s frequently required for business rents and agreements.
An approach consoles customers that you’ll have the option to repay them in the event that you harm their property or harm somebody with your work. Most entrepreneurs buy an arrangement soon after beginning a business. Peruse progressively about general obligation protection inclusion.
- Organizations that buy a general risk strategy ordinarily:
- Have an area that is available to the general population
- Communicate with individuals on a place of work
- Handle customer property
- Lease business space
- Offer items to clients
- Publicize or market their administrations
- Utilize web-based life and have a web nearness
- Proficient obligation protection
Digital obligation protection
Digital obligation protection can pay for costs if a business endures an information break or noxious programming assault, including client warning, credit checking, lawful charges, and fines Entrepreneur’s approach An entrepreneur’s approach, or BOP, joins general risk protection with business property protection, commonly at a lower rate than if the strategies were bought independently. Laborers’ pay protection Laborers’ pay protection is required in pretty much every state for organizations that have workers. It can take care of medicinal expenses and lost wages for business-related wounds.Business collision protection
Business collision protection can pay for property harm and doctor’s visit expenses in a mishap including a business-claimed vehicle. It additionally covers burglary and particular sorts of harm. Business collision protection enables to take care of for medicinal tabs and property to harm identified with a mishap in a business-claimed vehicle. It additionally covers vehicle burglary and different sorts of vehicle harm. Independent companies are required to buy business collision protection for business-possessed vehicles in pretty much every state. New Hampshire and Virginia are special cases, yet drivers are as yet liable for harms they cause – and the most ideal approach to take care of that expense is through protection.

Small
business Insurance
New York.
The city with several
small businesses
New York, also known as ‘The City’, is home to several small businesses. As a matter of fact, with almost 2 million small businesses, which makes a significant fraction of 99.75 of the total businesses present in New York, it is one of the leading cities in this regard. And, the most fantastic thing about NY is the diversity it represents in business owners as well as employees.
If you are a small business owner in New York or plan to start one, then do remember that the state laws can affect the insurance policies that one needs to own for starting a small business in the city.
The required policies of small business insurance in New York are mentioned as below-
Worker’s compensation Insurance— This insurance policy is known to cover medical bills for work-related injuries as well as protects the employees from liability over that injury.
Commercial auto insurance— By law, all those vehicles that are used for the business work are covered under commercial auto insurance. Under this insurance the requirements include- bodily injury liability of $25,000/ person whereas $50,000/ accident, property damage liability of $10,000/ season, liability for death of $50,000 /accident whereas $100,000/ accident and personal injury protection of $50,000.
What are the insurance policies that the state of New York mandates?
This is a known fact that the requirement of every business is different. At the same time, all the companies must consider the effect of protecting their business with the correct small business insurance NY. In this regard, some of the recommended insurance policies for small businesses in NY are mentioned as follows--
General liability Insurance-
- Professional liability insurance— The concerned policy, also known as errors and omissions, tends to protect those professionals who are experts in one or the other field. It further covers the lawsuits of clients over the mistakes as well as the deadlines that could not be completed on time.
- Cyber liability insurance—
- Business Owner’s Policy—
- Worker’s compensation insurance- If you own a small business in New York, then state law requires you and every small business owners that employ people, for part-time or full-time, to have worker’s compensation insurance covered. This is due to the reason that this policy provides medical costs for the injuries that employees can suffer while working.
- Commercial auto insurance—
Understanding
the Concept
of Business Insurance
With economic inflation prevailing across the globe it is essential to take business insurance to prevent yourself from business losses. Business owners are suffering a lot not only from a lack of orders and labor problems but also due to sudden damages caused by natural calamities and other accidents like fire accidents. Due to these kinds of situations, business owners will suffer a lot and to avoid this concept of business insurance has evolved. It protects the business owners from suffering sudden financial losses. In cities like New York, The small business insurance NY is best suited for the startups you can cover the maximum amount of your losses through this. The only thing you need to do is choose the right small business insurance New York from the reputed insurance company.
Small
business Insurance
in new York
With the growth in budgetary crisis, diverse little endeavors are being obliged to escape such risks by having a Small business Insurance in new York. Attestation union is the best way to deal with oversee stay protected and avowed from surprising damages and shocking liabilities. Different sorts of assurances are open in the market to investigate.
The essential concern every business will scan for, is high security returns to cover the mischief sensibly. It is generally basic for self-overseeing embarks to look for a right kind of plan for them.
The security plan that they look for, should: be cost useful, and gives a sufficient degree of thought You can request that a security administrator pick a sensible Commercial Insurance, Sydney for your business. Since, the necessities of every business are uncommon, you ought to be unequivocal, while looking for a perfect business insurance plan.
Here are a bit of the attestation packages that are must for the smooth working of a private endeavor, for instance, General Liability Insurance: A course of action related to the idea for any real exercises that are recorded against your business as a result of the remissness of your laborers. Such security plan is required as it gives true blue assistance to your business. Property Insurance: Another kind of assertion that a selective business must have.
It is a kind of affirmation plan that covers the hardships or damages of an affiliations working condition. It is required to watch your business property from trivial damages. A Small business Insurance in new York will connect with your business to complete validation against crude perils. Workers Compensation: A sort of security which is noteworthy for individuals. Under this affirmation plan, an operator gets a bit of leeway to sue their chief if there ought to be an event of any hands on wounds.
This security is unequivocally to shield the interests of laborers. Each master’s visit cost, or damages are in like manner affirmed under this kind of security plan. Near to this, there are altogether more security types open in the market. Plan to shield your business extraordinary conditions by getting a perfect independent affiliation affirmation union.
Small
business insurance
equirements in new era.
Independent company protection, at times called business protection, ensures a business’ advantages, property and pay. An entrepreneurs approach (BOP) is the most well-known arrangement for independent ventures, as indicated by the Insurance Information Institute.
A BOP ordinarily incorporates three fundamental kinds of inclusion to help ensure a business: business property inclusion, general obligation inclusion and business interference inclusion.
A BOP ordinarily incorporates three fundamental kinds of inclusion to help ensure a business: business property inclusion, general obligation inclusion and business interference inclusion.
In case you’re an entrepreneur, you may likewise have the option to purchase extra protection inclusions to tweak your arrangement dependent on your particular activity and requirements.
WHAT DOES SMALL BUSINESS INSURANCE COVER?
Contingent upon the inclusion you pick, an entrepreneurs approach secures your business against things like monetary misfortunes and secured risks. Secured risks may incorporate burglary, fire, wind, falling articles and lightning.
It’s essential to peruse your strategy records cautiously to comprehend which inclusions are incorporated and what risks are secured by your guarantor.
Every inclusion in your BOP has an inclusion limit. A breaking point is the most extreme sum your guarantor will pay for a secured case.
It’s additionally critical to take note of that every inclusion in an arrangement is normally dependent upon its own breaking point.
Furthermore, a few inclusions may accompany a deductible. A deductible is the measure of cash you pay out of pocket toward a secured case.
BUSINESS PROPERTY COVERAGE
The property inclusion in an entrepreneurs arrangement ensures your business’ structure and its substance against secured dangers. For instance, if there is a fire at your business, a BOP may help pay for building fixes (on the off chance that you claim the structure). This inclusion likewise replaces business property, for example, office furniture, PCs or apparatus. Remember that business property inclusion will be dependent upon a deductible and cutoff points. You can commonly pick your property inclusion limits dependent on the evaluated expense to fix, reconstruct or supplant your business’ property. Yet, in the event that your misfortunes surpass as far as possible you picked, you’ll at that point need to pay out of pocket to get done with building fixes or substitution of your business’ property. It’s essential to take note of that having deficient approach cutoff points may likewise bring about a punishment. This is a fine you’d have to pay for not obtaining enough protection. To help maintain a strategic distance from punishments, ensure you buy enough protection to cover your business and its substance.GENERAL LIABILITY COVERAGE
An entrepreneurs strategy for the most part incorporates general obligation inclusion (now and again called business general risk, or CGL). On the off chance that a client or guest is harmed at your business, and you’re discovered at risk, general obligation inclusion may help pay for the harmed party’s therapeutic costs. It might likewise help pay for lawful expenses in case you’re indicted over a mishap that happened at your business. It is very necessary to have small buisness insurance. Business general risk protection is likewise dependent upon an inclusion limit. That implies if a harmed individual’s hospital expenses surpass your inclusion limit, you may need to pay out of pocket to cover the rest.
GROWTH OF
SMALL BUSINESSES INCREASES
THE DEMAND FOR
INSURANCE IN NEWYORK
Recent research has been stated that the top rankingstate in entrepreneurship with 2.1 million small businesses is newyork which covers 99% of total businesses of entire state. On the other hand it is also leading state in providing employment to more than 3 million people which is equal to 50.6% of total working population of Newyork. Every year accelerating growth indicates that Demand for small businesses insurance is expected to rise in NY in upcoming years.It has been stated that small businesses in NY with fewer employees provided more than 4 million jobs with approx total payroll of $ 23 billion.
NEED FOR SMALL BUSINESS INSURANCE
IN NY:
Newyork is also hub for rapid commercial growth in various industries like Banking, finance, Publishing, foreign trade, tourism and manufacturing. As per the accelerating growth in all sectors and increasing employment ratedraws the attention towards the increasing demand of Insurance among small businesses.
TYPES OF SMALL BUSINESSES INSURANCE COVERGAES IN NEWYORK:
Four types of Small Business Insurance in NY helpto get coverage for losses:- General LiabilityInsurance:helps small business to get protected and get claim for business property damage, bodily injuries to employees during training sessions and personal injury losses.
- Business Owners Policy: it is the balanced mix of business liability insurance and business property insurance. It covers claims for damages occur from fire, theft and disasters. It also provides coverage for damages occurs through business operations which include property damage and bodily injury. As per the requirements it can also be extended for further additional coverage like data breach, professional liability and business income for off premises utility services
- Commercial Property Insurance: it includes coverage for things used in office which get damage due to fire or get damages from other reasons or things get stolen in offices. Some of the items covered under this insurance are office furniture, inventory, equipment and all personal items used for establishment of office.
- Business Income Insurance: covers the losses on revenue which has been incurred due to property loss, damage from disaster, fire, theft or storm damages. It helps thesmall businesses to get their lost income while covering from damages.
TLC
drivers can make up
to $400 per night
Learn how to earn up to $400 per night!!
Excelsior is pleased to announce a new program that will connect drivers to one of our vendors, to provide transportation to essential workers during the Metropolitan Transportation Authority’s nightly closures announced by Mayor Bill de Blasio and Gov. Andrew Cuomo last week.
The MTA will be closing the subways, beginning this Tuesday, May 5, from 1:00AM to 5:00AM every night during the pandemic so they can disinfect subway cars and protect essential workers during the coronavirus crisis.
Essential Workers Transportation Program Highlights:
Drivers can earn up to $400 a night As much as 15 to 20 thousand drivers are needed for the program Drivers in the program are eligible to work from 11:30PM to 6:00AM nightly It is understood that the program will continue until further noticeDrivers are urged to register for this program at
https://excelsiorfhv.com/EssentialWorkersTransportationProgram We believe that there will be a tremendous response to this program and urge you to immediately contact your drivers so that they can take advantage of this opportunity. Thank you for your continued support and please take care of yourself and family. In case you’ve questions, feel free to reach out to us either in the chat window or contact us at contact@ayroyal.com
Homeowners
Insurance in Florida:
Your Friendly Guide
to Securing Your Home
Introduction
Are you a homeowner in Florida? Wondering about homeowners insurance and why it’s crucial? This guide covers all you need to know about securing your home with the right insurance policy.
Overview of Homeowners Insurance
Importance of Homeowners Insurance in Florida
Homeowners insurance is essential in Florida due to the state’s susceptibility to natural disasters like hurricanes and floods. It protects your home and belongings from unforeseen damages, ensuring financial security and peace of mind.Who Needs Homeowners Insurance?
Every homeowner in Florida should consider homeowners insurance to safeguard against potential risks. It’s especially vital for those with mortgages, as lenders often require it.Understanding Homeowners Insurance
What is Homeowners Insurance?
Homeowners insurance is a policy that covers losses and damages to an individual’s house and assets in the home. It also provides liability coverage against accidents in the home or on the property.History and Evolution of Homeowners Insurance in Florida
Homeowners insurance in Florida has evolved significantly over the years. Initially, policies were basic, covering only fire and theft. With the increasing occurrence of natural disasters, the coverage has expanded to include a wide range of perils.
Types of Homeowners Insurance
| Type of Insurance | Coverage Details | Benefits and Limitations |
|---|---|---|
| Liability Insurance | Covers legal fees and damages if you’re sued for injury or property damage caused to others. | Benefit: Protects against lawsuits. Limitation: Does not cover intentional damage. |
| Collision Insurance | Covers repairs or replacement of your car if it’s damaged in an accident. | Benefit: Helps repair or replace vehicle. Limitation: Deductibles apply; doesn’t cover non-collision damage. |
| Comprehensive Insurance | Covers non-collision-related damages such as theft, fire, or natural disasters. | Benefit: Broad coverage. Limitation: Excludes collision-related incidents. |
| Personal Injury Protection (PIP) | Covers medical expenses and lost wages for you and your passengers after an accident. | Benefit: Immediate medical coverage. Limitation: Coverage limits may be low. |
| Uninsured/Underinsured Motorist | Covers injuries and damages if the at-fault driver doesn’t have sufficient insurance. | Benefit: Protection against underinsured drivers. Limitation: May not cover all expenses. |
Eligibility and Requirements
Who Qualifies for Homeowners Insurance?
Most homeowners in Florida qualify for homeowners insurance. Factors like home location, condition, and previous claims history can influence eligibility.Documentation Needed for Homeowners Insurance
To obtain homeowners insurance, you typically need proof of homeownership, property details, previous insurance records, and a home inspection report.Steps to Obtain Homeowners Insurance
- Research and compare insurance providers.
- Get a home inspection.
- Gather necessary documents.
- Request quotes from multiple insurers.
- Choose a policy that fits your needs and budget.
- Complete the application process.
Cost of Homeowners Insurance
Factors Affecting Homeowners Insurance Rates
Several factors impact homeowners insurance rates, including the home’s location, age, construction type, and your credit score.Average Costs in Florida
On average, homeowners in Florida pay around $1,500 annually for insurance, but this can vary widely based on the factors mentioned above.Ways to Reduce Homeowners Insurance Costs
- Increase your deductible.
- Install safety features like alarms and storm shutters.
- Bundle your policies.
- Maintain a good credit score.
Know-how’s When You Apply for Homeowners Insurance
Step-by-Step Application Process
- Gather all necessary documents.
- Fill out the application form accurately.
- Submit the application and required documents.
- Await the insurer’s review and approval.
Online vs. In-Person Application
| Method | Pros | Cons |
|---|---|---|
| Online Application | Convenient, quick processing, 24/7 availability | Less personalized service, potential technical issues |
| In-Person Application | Personalized service, immediate assistance with questions | May take more time, limited to business hours |
Tips for a Smooth Application Experience
- Double-check all information before submitting.
- Keep all required documents handy.
- Be honest and accurate in your application.
Common Issues and Solutions
Denied Applications
Common Reasons for Denial
- High-risk location.
- Poor home condition.
- Previous insurance claims.
Steps to Reapply
- Address the issues that led to denial.
- Improve home safety features.
- Reapply with a different insurer.
Claim Disputes
How to Handle Claim Disputes
- Review your policy details.
- Gather all relevant documentation.
- Contact your insurance company for clarification.
Legal Options Available
If disputes are unresolved, consider legal counsel or contacting your state insurance department for assistance.Homeowners Insurance for Different Vehicles
| Vehicle Type | Specific Requirements | Coverage |
|---|---|---|
| Taxis | Commercial insurance, higher coverage limits | Coverage for passengers and vehicle damage |
| Rideshare Vehicles | Rideshare insurance, personal and commercial coverage | Coverage during rideshare activities and personal use |
| Limousines | Luxury vehicle insurance, high liability coverage | Comprehensive coverage for high-value vehicles |
| Black Cars | Commercial insurance, luxury vehicle coverage | Coverage for passengers, high-value vehicle damage |
Legal and Regulatory Aspects
Florida Homeowners Insurance Regulations and Compliance
Florida has specific regulations to ensure homeowners insurance policies provide adequate coverage. Insurers must comply with state guidelines to protect homeowners.Impact of Regulations on Homeowners Insurance
Regulations ensure fair practices and adequate coverage, but they can also lead to higher premiums due to mandatory coverages.Recent Changes in Homeowners Insurance Laws
Recent updates include stricter building codes and enhanced coverage requirements for flood-prone areas to better protect homeowners.Conclusion
Recap of Key Points
- Homeowners insurance is crucial for financial security in Florida.
- Understand different types and costs.
- Follow the application process carefully.
Importance of Staying Informed about Homeowners Insurance
Stay updated on insurance laws and available discounts to ensure you have the best coverage for your needs.Final Thoughts
Securing your home with the right insurance policy brings peace of mind. Make informed decisions to protect your valuable investment.FAQs
What is the minimum coverage required for homeowners insurance in Florida? The minimum coverage typically includes protection for the home structure, personal property, and liability. Specific requirements may vary by insurer. How long does it take to get approved for homeowners insurance? Approval can take anywhere from a few days to a couple of weeks, depending on the insurer and completeness of your application. Can I switch homeowners insurance providers? Yes, you can switch providers at any time. Make sure to compare policies and understand any cancellation fees. What happens if my homeowners insurance lapses? If your insurance lapses, you will be without coverage, putting your home at risk. Additionally, your mortgage lender may purchase insurance on your behalf, which could be more expensive. Are there any discounts available for homeowners insurance? Yes, discounts are often available for installing safety features, bundling policies, having a good credit score, and more.
Homeowners
Insurance in New Jersey:
Your Essential Guide
Are you a homeowner in New Jersey? Curious about what homeowners insurance is, why it’s crucial, and who needs it? This guide will answer these questions and more, providing you with all the essential information on homeowners insurance in New Jersey.
Overview of Homeowners Insurance
Importance of Homeowners Insurance in New Jersey
Homeowners insurance in New Jersey is vital due to the state’s diverse weather conditions, potential natural disasters, and everyday risks. It protects your home and personal property from damages and losses, offering peace of mind.Who Needs Homeowners Insurance?
Every homeowner in New Jersey should have homeowners insurance. Whether you own a single-family home, a condo, or a townhouse, this insurance safeguards your investment and covers unexpected events like theft, fire, or natural disasters.Understanding Homeowners Insurance
What is Homeowners Insurance?
Homeowners insurance is a policy that protects your home and belongings against damages and losses. It covers events like fire, theft, and natural disasters, and also provides liability coverage if someone is injured on your property.History and Evolution of Homeowners Insurance in New Jersey
Homeowners insurance has evolved significantly in New Jersey. Initially offering basic fire and theft protection, it now includes comprehensive coverage options reflecting the diverse needs of homeowners and changing environmental risks.
Types of Homeowners Insurance
| Type of Insurance | Coverage Details | Benefits and Limitations |
|---|---|---|
| Liability Insurance | Covers bodily injury and property damage if someone is injured on your property. | Benefit: Essential for legal compliance. Limitation: Doesn’t cover damages to your property. |
| Collision Insurance | Not typically part of homeowners insurance (related to auto insurance). | N/A |
| Comprehensive Insurance | Covers various risks including theft, fire, and natural disasters. | Benefit: Broad protection. Limitation: Excludes certain perils like floods without additional coverage. |
| Personal Injury Protection (PIP) | Covers medical expenses and lost wages for injuries occurring on your property. | Benefit: Immediate medical coverage. Limitation: Coverage limits may be low. |
| Uninsured/Underinsured Motorist | Not applicable to homeowners insurance (related to auto insurance). | N/A |
Eligibility and Requirements
Who Qualifies for Homeowners Insurance?
Any homeowner or property owner in New Jersey qualifies for homeowners insurance. This includes owners of single-family homes, condos, townhouses, and rental properties.Documentation Needed for Homeowners Insurance
To obtain homeowners insurance, you typically need:- Proof of homeownership
- Property details (size, location, construction type)
- Home value and contents estimation
- Previous insurance records
Steps to Obtain Homeowners Insurance
- Assess your coverage needs.
- Research and compare insurance providers.
- Gather necessary documents.
- Request quotes from multiple insurers.
- Choose a policy that fits your needs and budget.
- Complete the application process.
Cost of Homeowners Insurance
Factors Affecting Homeowners Insurance Rates
Several factors impact homeowners insurance rates, including:- Home location
- Home age and construction type
- Coverage limits and deductibles
- Claims history
- Security features
Average Costs in New Jersey
On average, homeowners insurance in New Jersey costs around $1,200 to $2,000 per year. Rates vary based on the factors mentioned above.Ways to Reduce Homeowners Insurance Costs
- Increase your deductible.
- Install security systems.
- Bundle policies.
- Maintain a claims-free history.
- Regularly review and update your coverage.
Know-how’s When You Apply for Homeowners Insurance
Step-by-Step Application Process
- Gather all necessary documents.
- Fill out the application form accurately.
- Submit the application and required documents.
- Await the insurer’s review and approval.
Online vs. In-Person Application
| Method | Pros | Cons |
|---|---|---|
| Online Application | Convenient, quick processing, 24/7 availability | Less personalized service, potential technical issues |
| In-Person Application | Personalized service, immediate assistance with questions | May take more time, limited to business hours |
Tips for a Smooth Application Experience
- Double-check all information before submitting.
- Keep all required documents handy.
- Be honest and accurate in your application.
Common Issues and Solutions
Denied Applications
Common Reasons for Denial
- High-risk property.
- Incomplete or inaccurate information.
- High claims history.
Steps to Reapply
- Address the issues that led to denial.
- Make necessary improvements to your property.
- Reapply with accurate and complete information.
Claim Disputes
How to Handle Claim Disputes
- Review your policy details.
- Gather all relevant documentation.
- Contact your insurance company for clarification.
Legal Options Available
If disputes are unresolved, consider legal counsel or contacting your state insurance department for assistance.Homeowners Insurance for Different Properties
| Property Type | Specific Requirements | Coverage |
|---|---|---|
| Single-Family Homes | Standard homeowners insurance | Comprehensive coverage for structure and contents |
| Condos | Condo insurance (covers interior and contents) | Coverage for personal property and interior damages |
| Townhouses | Homeowners or condo insurance, depending on HOA | Comprehensive coverage for structure and contents |
| Rental Properties | Landlord insurance | Coverage for building, liability, and loss of rent |
Legal and Regulatory Aspects
New Jersey Homeowners Insurance Regulations and Compliance
New Jersey has specific regulations to ensure homeowners insurance policies provide adequate coverage. Insurers must comply with state guidelines to protect homeowners.Impact of Regulations on Homeowners Insurance
Regulations ensure fair practices and adequate coverage, but they can also lead to higher premiums due to mandatory coverages.Recent Changes in Homeowners Insurance Laws
Recent updates include stricter safety requirements and enhanced coverage mandates for homes in high-risk areas to ensure better protection.Conclusion
Recap of Key Points
- Homeowners insurance is essential for protecting your home and belongings in New Jersey.
- Understand different types and costs.
- Follow the application process carefully.
Importance of Staying Informed about Homeowners Insurance
Stay updated on insurance laws and available discounts to ensure you have the best coverage for your home.Final Thoughts
Securing your home with the right insurance policy brings peace of mind. Make informed decisions to protect your valuable assets.FAQs
What is the minimum coverage required for homeowners insurance in New Jersey? The minimum coverage typically includes liability insurance and coverage for the home’s structure and personal property. Specific requirements may vary by insurer. How long does it take to get approved for homeowners insurance? Approval can take anywhere from a few days to a couple of weeks, depending on the insurer and completeness of your application. Can I switch homeowners insurance providers? Yes, you can switch providers at any time. Make sure to compare policies and understand any cancellation fees. What happens if my homeowners insurance lapses? If your insurance lapses, you will be without coverage, putting your home at risk. Additionally, you may face higher premiums or difficulties obtaining coverage in the future. Are there any discounts available for homeowners insurance? Yes, discounts are often available for installing security systems, bundling policies, maintaining a claims-free history, and more.
FHV
Vehicle License
Storage
The New York City Taxi and Limousine Commission has made a provision of putting your vehicle’s license within the storage for a 180 day tenure as long as you’re not operating your vehicle. License, standing as an essentially powerful proof for your FHV vehicle identity, may be a must carry self-claim authority along.
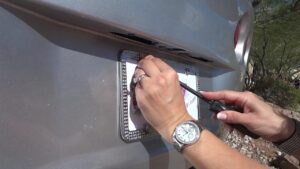
How to Put my TLC for-hire-vehicle license in Storage?
TLC grants only a 1 time permission for putting your license in storage. Needless to stress about the compliance and fee because it isn’t mandatory to place your license in storage supplying you with a smooth edge over your continuous operation and job. Also, TLC doesn’t demand any fee for license storage, again, giving its customers leverage to store their license within the trough occupation seasons. Following is detailed information to coat clarity about ‘how to place TLC FHV license in storage?’ : i) Department of automobiles (DMV) is the sole authority for registering vehicles, issuing licenses, processing storage requirements and lots of others within the same row. As such, your first move should be to surrender your TLC plate to the DMV. ii) you’re , after which, given a form with some mutual compliance and Terms & Conditions for the upcoming proceedings requiring you to refill section 1 & section 2. iii) you’re then required to mail the filled up form to the FHV website after proper scanning. You, thus, inform DMV that the TLC decals are removed and are eligible for putting your license in storage. https://youtu.be/H2Ad-tOS6I4Where can I pay for the transfer?
All you would like to try to do for payment is to click on the prevailing TLC license, enter the vehicle registration number mentioned within the diamond sticker and also put in your postcode . If you receive the mail from TLC regarding the confirmation and acceptance of your transfer documents, you’ll proceed with fee payment ; before which you can’t .How am I able to remove my TLC For-hire-vehicle from storage?
Although you’re alleged to deposit your TLC plates but if it still remains with you while your vehicle license is in storage, you’ll choose the alternatives where in you’re required to fill section 3 of FHV storage request form, invite the updated insurance certificate from the broker you’re in-tuned with then mail the certificate along side FHV request form to FHV website for removing your license from storage after due inspection. The similar procedure would entail post your TLC plate surrender. Only you would like to finish the transfer application for getting new plates and later, catch hold of appointments at the TLC office for renewal and reception of latest TLC plates.FHV License storage
If you discover 130 days are way enough for an extended sitting at an area and need to modify back to job i.e. want to urge license back from storage before 180 days completion, you’re at liberty to withdraw your license back from storage with the underlying condition that the license can’t be shifted back to storage once scrapped. Be sure to surrender only custom plates at the DMV office; for the quality vehicle plates aren’t subtly processed or assessed and may be destroyed.How am I able to replace my personalized plates?
DMV has made provisions for renewal, remakes or reimbursements just in case of need by its customer. Let’s say, your personalized plate must be exchanged with a clearer and newer one because it can not provide utility. For this, you’ll approach the custom plates unit at their customized time and obtain the proceedings and formalities finished renewal applications ahead. There’s also equal occupancy for Excelsior style which you’ll enquire at an equivalent place. If your idea is inclined towards purchasing an altogether new vehicle, you can contact the DMV office and obtain personalized plates transferred to the new vehicle once it’s registered. To be precise and specific about the pandemic time, TLC, for the nonce , is limiting its new FHV licenses issuance for wheelchair accessible vehicles. The time boundaries and external commitments brings all the services for folk to a near standstill; starting super soon once the situations normalize.
About Wheelchair accessible Vehicle
For a vehicle to maneuver from able and fit user domain to disable user domain, it must fulfill ADA specifications and legit vehicle modifier approval after which it can be considered as a wheelchair accessible vehicle.Conclusion
TLC has rigid rules for vehicle license and you can’t operate a vehicle on road unless it’s registered ; deeming an automobile race or public travel is indeed a far-sighted thought if the vehicle isn’t legally eligible for transportation purpose (has license). Another most vital requirement is that the insurance of FHV vehicles not just for the security of your front and back seat passengers but as a protective and persuasive repo presenting the price it offers by virtue of its relentless services. One of the simplest TLC insurance services you get in New York city is by A&Y Royal insurance supplying you with end to finish service alongside relentless after sales services.